Daniel Chu’s Tricolor Fraud Case Slid Toward a January 2027 Trial After Cooperators and an SEC Suit


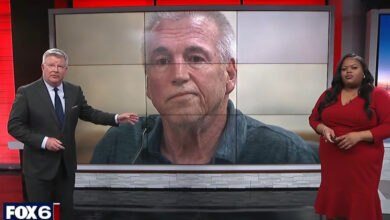
Daniel Chu is not in a jury box this week. The founder of Tricolor Holdings was supposed to start a criminal trial in Manhattan on October 19, 2026. That date was the one Judge P. Kevin Castel set in the spring, when the case was still a four-count fight about warehouse loans. By late July the calendar had moved. Courtroom reporting of a July 30, 2026 minute entry says speedy-trial time was excluded until a trial date of January 25, 2027, after a July 7 order that would adjourn the October setting and put a final pretrial conference on December 9 if the parties filed a workable schedule. The public docket was still being written on September 23, with letter motions the day before and a memo endorsement the day after. Chu, 62, of Miami, remains out on bail. He has pleaded not guilty. The people who already admitted the fraud are not going to that trial with him.
The delay is the story that bond buyers should actually read. Tricolor was a used-car retailer and subprime lender for buyers prime banks would not touch, including people with thin files and, in many cases, no Social Security number. The pitch to Wall Street was that the loans were real, the cars were titled, and each securitization pool was free and clear. Prosecutors say the paper was pledged twice. The Securities and Exchange Commission, in a civil complaint filed August 18, 2026, put a number on the bond side of the same wreck: more than $1.9 billion raised through asset-backed securities from at least 2020 until the September 2025 bankruptcy, with more than $945 million of principal still outstanding when the company died.
Two clocks, one pile of cars
The Department of Justice case and the SEC case share a cast and split a theory. Prosecutors say Chu lied to warehouse lenders and, after a June 24, 2026 superseding indictment, to the people who bought the bonds. The eight-count indictment added bank-fraud and wire-fraud counts tied to an SPV5 warehouse facility, plus conspiracy to commit securities fraud and a substantive securities-fraud count. The SEC complaint, SEC v. Chu, Kollar, and Seibold, No. 26-civ-7041 in the Southern District of New York, charges the same three men with antifraud violations of the Securities Act and the Exchange Act, adds control-person liability against Chu, and adds aiding-and-abetting counts. The agency wants injunctions, disgorgement, civil penalties, and officer-and-director bars against Chu and former chief financial officer Jerome Kollar. The release is SEC 2026-77.
The original criminal theory was blunt. Pledge the same auto-loan receivable to more than one warehouse line so the company could draw cash it had already spent. Then massage defaulted or near-dead accounts until they looked current enough to dump into a securitization. By August 2025, the government says, Tricolor had pledged about $2.2 billion of collateral against roughly $1.4 billion of actual loans. That is an $800 million hole. About 29,000 loans were promised to two masters at once. Jay Clayton, the U.S. attorney, said Tricolor repeatedly lied to banks and other credit providers by falsifying auto-loan data and double-pledging collateral.
Chu was charged with running a continuing financial-crimes enterprise, a rarely used statute that carries a 10-year mandatory minimum and a life maximum, plus bank fraud, wire fraud, securities fraud, and conspiracy. He pleaded not guilty on January 13, 2026. In August a judge refused to throw out the kingpin count. His lawyer, Matthew Schwartz, called the SEC case a rehash of allegations already made and said many of them are inaccurate and will look different when the facts come out. That is a defense. It is not a dismissal.
The room that already pleaded
David Goodgame, the former chief operating officer, pleaded guilty on June 24, 2026, the same day the superseding indictment landed on Chu alone. The information covered six counts: conspiracy to commit bank fraud and wire fraud affecting a financial institution, bank fraud, wire fraud affecting a financial institution, conspiracy to commit securities fraud, securities fraud, and making materially false statements to FBI agents on or about October 20, 2025 about the existence, nature, and value of the pledged collateral. Standing in front of Castel, Goodgame said he knew Tricolor was deceiving banks, that executives were manipulating data, and that he had raised the problem with Chu. He agreed to cooperate. Kollar and former senior finance director Ameryn Seibold pleaded guilty in December 2025 and are also cooperating. In late July, Chu’s team asked to unseal those plea transcripts. The court allowed it.
That is the room a January jury would walk into if the minute entry holds: three former officers already talking, and a founder who still wants twelve strangers. Cooperation calendars are built this way on purpose. The helper waits. The trial of the boss produces a record a judge can score at sentencing. Goodgame’s exposure on the fraud counts can reach decades. The false-statement count is its own problem. Lying to agents after the company is already dead is how a cooperator loses the benefit of the doubt before he ever takes the stand for the government.
Bonuses, a house, and a Chapter 7
The criminal narrative is not only about double pledging. Prosecutors say Chu took $19.3 million in salary and bonuses between August 2023 and August 2025, then ordered the last $6.25 million of a $15 million bonus paid on August 19 and 20, 2025. That was weeks before more than 1,000 workers were sent home without pay. Around August 27 he closed on a multimillion-dollar Beverly Hills property. Tricolor filed Chapter 7 on September 10, 2025, owing warehouse lenders more than $900 million. Certain lenders had uncovered the hole in the summer and called the debt in early September. On recorded calls, the government says Chu floated fake deferment policies to explain audit gaps and compared the mess to Enron. JPMorgan booked about $170 million in losses. Fifth Third flagged exposure up to $200 million. Jamie Dimon’s line about cockroaches made the business pages because private-credit desks had been selling the paper as quiet yield. The bankruptcy trustee called the fraud extraordinary.
Tricolor’s customers did not get that press conference. The company had marketed itself as a ladder for buyers who needed a car to keep a job. When the lender collapsed, a backup servicer kept collecting on surviving loans while the Chapter 7 trustee liquidated inventory. The people making payments are still on the hook. Readers who followed The AEGIS Alliance’s reporting on the 700Credit breach that exposed nearly six million car buyers already know how much of a modern lot runs through third-party pipes. Tricolor is what happens when the pipe is the product and the product is pledged twice. The debt-relief industry will try to sell those same borrowers a second product.
Why January is not a footnote
Warehouse fraud is a lender problem. Securities fraud is an investor problem. The ABS buyers who were told the pools were clean now have a civil theory that does not depend on a criminal verdict. That matters if a jury in January hangs, or if Chu’s team chips the kingpin count down to ordinary fraud. The SEC case can still seek disgorgement and bars if the criminal docket slips again. Underwriters who relied on Tricolor’s representations are already inside the discovery blast radius of both files. Castel’s own July language, as quoted from the bench file, said discovery was already adequate for a fair October trial. He moved the date anyway. Defense lawyers at two large firms had argued that four new counts, a new securities theory, Goodgame’s flip, and hundreds of thousands of late documents made a 2026 jury unfair. The government had said an adjournment would cheat victims and bankruptcy creditors who wanted a prompt record. The minute entry picked the later date and kept Chu on bail.
The private-credit angle is why this collapse traveled beyond auto desks. Tricolor raised bond money in the same market that funds equipment leases and point-of-sale loans. When Dimon talked about cockroaches, he was warning that one sloppy warehouse might not be the only one. First Brands blew up in the same season. The two names are now a paired case study in how fast consumer receivables can turn into a hole.
Chu is presumed innocent on the counts that remain. Kollar, Seibold, and Goodgame have already told a court they are not. A jury, if it sits, will hear a simple story: loans promised to two places, defaults dressed as current, money taken out while the books were already broken. The continuing-financial-crimes-enterprise count is the swing piece.
Outside the courthouse, subprime originations do not pause because a founder has a trial date. Demand for a car does not vanish. What changes is the warehouse. Banks that ate Tricolor losses will write tighter eligibility tests, demand more audit rights, and treat free-and-clear language as a clause they actually test. That is expensive. It is also how a market pretends it learned something while the borrowers keep paying a dead lender’s notes.
The AEGIS Alliance will keep following the file the same way it follows other financial wrecks in the business and crime coverage: by the documents, not by the brand. A January trial can still slip. The SEC case will still be there the morning after. So will the people whose cars were the collateral.