SEC Sues Tricolor CEO Daniel Chu After $1.9 Billion Subprime Collapse and Double-Pledged Auto Loans


Daniel Chu built Tricolor Holdings as a used-car lot and subprime lender for buyers the prime banks would not touch. Many of those buyers had thin files. Some had no Social Security number. The pitch to Wall Street was that the loans were real, the cars were titled, and the paper in each securitization pool was free and clear. On December 17, 2025, Manhattan federal prosecutors said the paper was pledged twice. On August 18, 2026, the Securities and Exchange Commission filed the civil twin and put a number on the bond side of the same wreck: more than $1.9 billion raised through asset-backed securities from at least 2020 until the September 2025 bankruptcy, with more than $945 million of principal still sitting on investors when the company died.
The two cases share a cast and split a theory. The Department of Justice says Chu and his operations chief lied to warehouse lenders. The SEC says Chu, former chief financial officer Jerome Kollar, and former senior finance director Ameryn Seibold lied to the people who bought the bonds those loans were supposed to support. Same collateral. Two clocks. One October trial date.
The double pledge
Prosecutors unsealed the original indictment the same week Tricolor’s name hit every business desk. They described two tricks. First, pledge the same auto-loan receivable to more than one warehouse line so the company could draw cash it had already spent. Second, massage defaulted or near-dead accounts until they looked current enough to dump into a securitization pool. By August 2025, the government says, Tricolor had pledged about $2.2 billion of collateral against roughly $1.4 billion of actual loans. That is an $800 million hole. About 29,000 loans were promised to two masters at once.
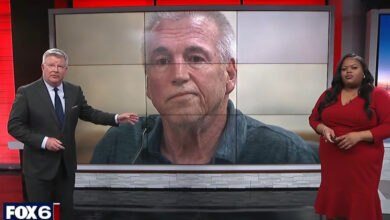
Chu, 62, of Miami, was charged with running a continuing financial-crimes enterprise, a rarely used statute that carries a 10-year mandatory minimum and a life maximum, plus bank fraud, wire fraud, securities fraud, and conspiracy. He pleaded not guilty on January 13, 2026. On June 24, 2026, prosecutors unsealed a superseding eight-count indictment and added more weight to the kingpin count. On August 14, a judge refused to throw that count out. Trial before U.S. District Judge Kevin Castel is set for October 19, 2026. Chu’s lawyers have asked for more time, citing the new charges and what they call slow discovery.
David Goodgame, the former chief operating officer, pleaded guilty in June 2026 to fraud and conspiracy counts that can reach 30 years. Standing in front of Castel, he said he knew Tricolor was deceiving banks, that executives were manipulating data, and that he had raised the problem with Chu. He agreed to cooperate. Kollar and Seibold pleaded guilty in December 2025 and are also cooperating. That is the room the SEC walked into in August: three former officers already talking, and a founder who still wants a jury.
The SEC complaint, filed in the Southern District of New York as SEC v. Chu, Kollar, and Seibold, No. 26-civ-7041, charges all three with antifraud violations of the Securities Act and the Exchange Act. It adds control-person liability against Chu and aiding-and-abetting counts against the group. The agency wants injunctions, disgorgement, civil penalties, and officer-and-director bars against Chu and Kollar. The full release is SEC 2026-77.
Bonuses, a Beverly Hills closing, and a Chapter 7
The criminal narrative is not only about double pledging. It is about what Chu did with the cash while the hole widened. Prosecutors say he took $19.3 million in salary and bonuses between August 2023 and August 2025, then ordered the last $6.25 million of a $15 million bonus paid on August 19 and 20, 2025. That was three weeks before more than 1,000 workers were sent home without pay. Around August 27 he closed on a multimillion-dollar Beverly Hills property. Tricolor filed Chapter 7 on September 10, owing warehouse lenders more than $900 million.
On secretly recorded calls, the government says Chu floated fake deferment policies to explain audit gaps and compared the mess to Enron. JPMorgan booked about $170 million in losses. Fifth Third flagged exposure up to $200 million. Jamie Dimon’s «cockroaches» line made the business pages because private-credit desks had been selling Tricolor paper as a quiet yield. The bankruptcy trustee called the fraud «extraordinary» and sued over a $38 million real-estate collection the trustee says was built on the bonus stream.
Tricolor’s customers did not get that press conference. The company had marketed itself as a ladder for immigrant and subprime buyers who needed a car to keep a job. When the lender collapsed, backup servicer Vervent kept collecting on the surviving loans while the Chapter 7 trustee liquidated inventory. The people making payments on those cars are still on the hook. The people who packaged the paper are in federal court.
Readers who followed The AEGIS Alliance’s reporting on the 700Credit breach that exposed nearly six million car buyers already know how much of a modern lot runs through third-party pipes. Tricolor is what happens when the pipe is the product and the product is pledged twice. The debt-relief industry will try to sell those same borrowers a second product. The banks will try to sell the story as a one-off.
Why the SEC filing changes the map
Warehouse fraud is a lender problem. Securities fraud is an investor problem. The ABS buyers who were told the pools were clean now have a civil theory that does not depend on a criminal verdict. That matters if a jury in October hangs, or if Chu’s team chips the kingpin count down to ordinary fraud. The SEC case can still seek disgorgement and bars even if the criminal docket slips. Underwriters who relied on Tricolor’s representations are already in the discovery blast radius of both files.
The private-credit angle is why this collapse traveled beyond auto desks. Tricolor was not a shadowy shop in a strip mall. It raised bond money in the same market that funds everything from equipment leases to point-of-sale loans. When Dimon talked about cockroaches, he was warning that one sloppy warehouse might not be the only sloppy warehouse. First Brands blew up in the same season. The two names are now a paired case study in how fast «granular consumer receivables» can turn into a hole.
Chu is presumed innocent on the counts that remain. Kollar, Seibold, and Goodgame have already told a court they are not. Goodgame’s sentencing control date has been discussed as far out as December 2026, which is how cooperation calendars work: the helper waits while the trial of the boss produces a record the judge can score.
What a jury will be asked to decide
The government’s story is simple on purpose. Loans were promised to two places. Defaults were dressed as current. Executives took money out while the books were already broken. Chu’s defense has pointed at a chaotic growth shop, at colleagues who are now bargaining, and at a trustee fight over houses. Juries have bought both versions in other fraud rooms. They have also sent founders away for decades when the recordings are ugly enough.
The continuing-financial-crimes-enterprise count is the swing piece. It is the statute prosecutors pull when they want a jury to see a boss, not a sloppy CFO. Defense lawyers hate it because the mandatory minimum removes the usual sentencing air. That is why the August ruling keeping the count alive is the most important pretrial paper in the file. If it survives to opening statements, the jury will hear «kingpin» before it hears «auto loan.»
Outside the courthouse, the used-car business has not paused. Subprime originations always rebound after a scandal because the demand does not vanish. What changes is the warehouse. Banks that ate Tricolor losses will write tighter eligibility tests, demand more audit rights, and treat «free and clear» language as a clause they actually test. That is expensive. It is also how a market pretends it learned something.
The AEGIS Alliance will keep following the October trial the same way it follows other financial wrecks in the business and crime files: by the documents, not by the brand. Chu can still walk if a jury rejects the tapes. The SEC case will still be there on Monday morning. The borrowers making payments on cars bought from a dead lender will still be there too.